Want more from Front Office Sports
in your search results?
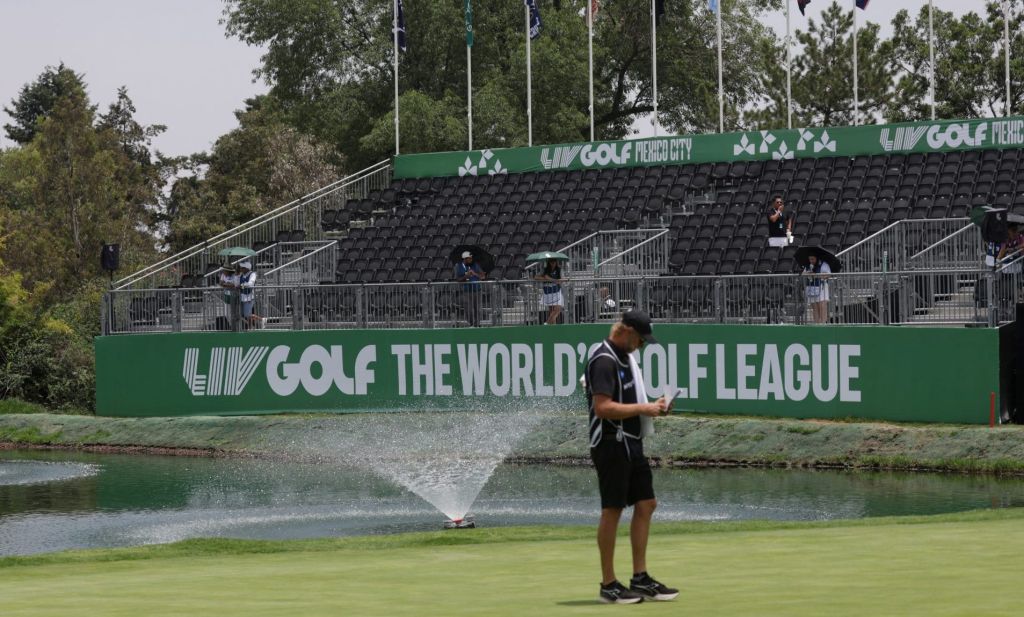
The prospects for unpaid vendors and contractors in LIV Golf’s Chapter 11 bankruptcy case are not good after the league announced plans to initiate the process of winding down operations.
“The outlook for unsecured creditors is likely quite bleak,” bankruptcy attorney John J. Sparacino, a principal at McKool Smith, tells Front Office Sports.
There are more than $100 million in claims from LIV’s unsecured creditors, but currently just $2 million set aside for recovery of those claims. “Depending on the size of the claim pool, that money would be allocated to those parties,” LIV’s chief restructuring officer David Orlofsky said during a creditors meeting on Oct. 15. “Obviously, that number may change over time, but that’s kind of what’s on the table at the moment.”
LIV’s unsecured creditors committee is hopeful that $2 million turns into much more, sources familiar with the committee’s thinking tell FOS, even if it’s an uphill battle. “It’s safe to say that’s not a number they’re comfortable with,” one source says. Potential sources of recovery for those extra funds could come from more claims against the Saudi PIF (LIV’s former financial backer), third parties, and LIV employees, among others. The creditors committee is represented by New York-based law firm Willkie Farr & Gallagher and New Jersey-based Fox Rothschild.
LIV players accounted for 14 of the 30 largest unsecured creditors when the league filed for bankruptcy on Sept. 8. But many other individuals and companies were listed, too, including agencies like IMG Media ($3.2 million) and GSE Worldwide ($1.28 million), golf influencer Rick Shiels ($1.39 million), the state of Louisiana ($1.22 million), and production company Fresh Tape Media ($1.2 million). The goal of the creditors committee is to maximize value for the group as a whole, sources say.
The Saudi PIF is LIV’s largest creditor, since the nearly $500 million of funding it gave the league to finish the 2026 season came in the form of a secured loan. That gave the PIF control of LIV’s bankruptcy, and the sovereign wealth fund put up $49.6 million in debtor-in-possession (DIP) financing to fund the bankruptcy process. The PIF could theoretically choose to increase the $2 million “pot plan” for unsecured claims, but most experts agree that’s unlikely.
“With where this case is going, it’s hard to imagine that there will be any material recoveries to really anyone,” Joe Bain, co-chair of law firm Jones Walker’s bankruptcy and restructuring team, tells FOS. Sparacino says “there is likely to be virtually nothing to distribute to unsecured creditors” and that he suspects “trade vendors will get little or no recovery.”
LIV is set to file its new Chapter 11 wind-down plan on Monday, which could have more details about paying out unsecured claims. The creditors committee is scheduled to meet next on Nov. 20.
One outside-the-box option for creditors could be trying to claw back money from the seven LIV executives who received more than $15.6 million in retention bonuses in June and August, since those payments were paid within the 90 days before LIV filed for bankruptcy. Brooklyn Law School professor Jodi Balsam, a former counsel for the NFL, outlined this idea on The Trey Wingo Show.
Download the FOS App
The business of sports, in your pocket.
Scan the QR code to get the app now.