Want more from Front Office Sports
in your search results?
Wall Street is showing unprecedented dissatisfaction with publicly traded ticket resellers, even as live sports hit a historic high.
Chicago-based Vivid Seats missed revenue and earnings targets in third-quarter earnings released this week, and the company could soon face a second reverse stock split to maintain its listing on Nasdaq. Despite growing sales, the company remains unprofitable. It has also seen its share value decline by nearly 80% this year to just $1.49, and its market capitalization now stands at less than $17 million.
Vivid Seats was worth nearly $2 billion when it first went public in 2021.
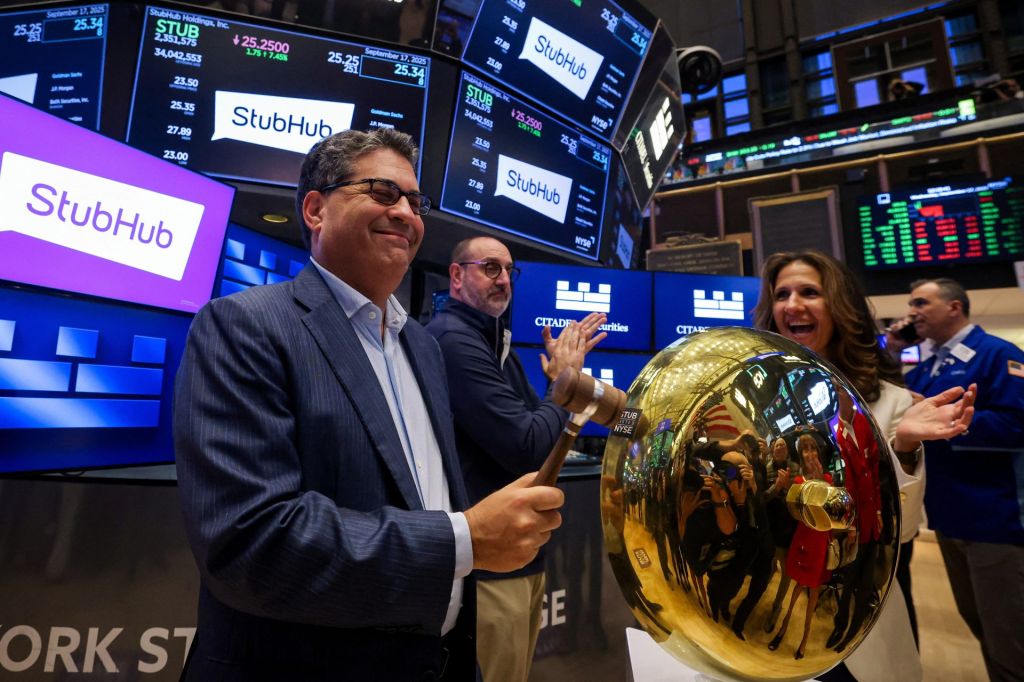
StubHub, which did much to legitimize the secondary ticket market early this century, had a similar story in its quarterly earnings released late Tuesday. Its quarterly revenue of $502 million and net income of $33.6 million also missed analyst targets. Its stock is down by more than 60% this year, and shares tumbled another 4.4% in after-hours trading Tuesday.
After initially targeting an initial public offering valuation of $9.2 billion last year—and ultimately getting to $8.6 billion—the StubHub market capitalization has since plummeted to about $2.2 billion.
Those results happened despite a robust sports calendar in the third quarter that included the concluding portion of the FIFA men’s World Cup and the start of the college football and NFL seasons.
Market Forces
The financial issues facing Vivid Seats and StubHub reflect a powerful combination of factors, including pricing and inventory pressure from several ticket resale marketplace competitors, the weight of substantial debt, heightened regulation, and internal missteps.
StubHub is also facing scrutiny from government regulators in several countries. In particular, Democrats in the U.S. House of Representatives are seeking more information on StubHub CEO Eric Baker’s simultaneous work as managing director of Andro Capital Management, another ticket resale firm. That relationship has raised suspicions of “market manipulation and self-dealing” and is also the subject of a consumer lawsuit that is now moving to arbitration.
Many of the ticket marketplaces’ top rivals are privately owned or venture-backed, including Gametime and SeatGeek. The latter has considered an IPO at multiple points but never filed to go public. The industry’s largest operator, Ticketmaster parent company Live Nation, is publicly traded and reported a series of double-digit increases in revenue, operating income, and event attendance last week. The vast majority of that company’s operations and financial heft, however, rest with its concert promotion business as opposed to Ticketmaster.
Vivid Seats, meanwhile, is seeking to stabilize itself with a recapitalization plan that will reduce its overall debt by about $200 million. Much of that effort, however, involves converting “a significant portion of existing debt into equity,” which will dilute existing shareholders, though it’s not yet clear by exactly how much.
“We’ve been in discussion with our lender group for a number of months. Implied in that is that numerous different approaches and structures were discussed and contemplated, ultimately [with a] need to find a path that works for the various constituencies collectively,” Vivid Seats CEO Lawrence Fey said in an earnings call with analysts. “I think more details coming in the coming days will kind of illuminate how everyone came to view this as a compelling and exciting path for everybody. But it’s safe to assume that many paths were examined exhaustively over the prior six months.”
Investment bank Craig-Hallum downgraded its rating of Vivid Seats shares to a hold, writing that it struggled to see a “captivating upside scenario” given the wide range of issues facing the company.
Download the FOS App
The business of sports, in your pocket.
Scan the QR code to get the app now.